Gold Education · Gold Investing · 8 MIN READ
Allocated vs. Unallocated Gold: What Do You Actually Own?
Allocated gold gives an owner title to identified metal, while an unallocated account is generally a claim against a provider. Learn the practical risks, costs, and questions to ask before buying.
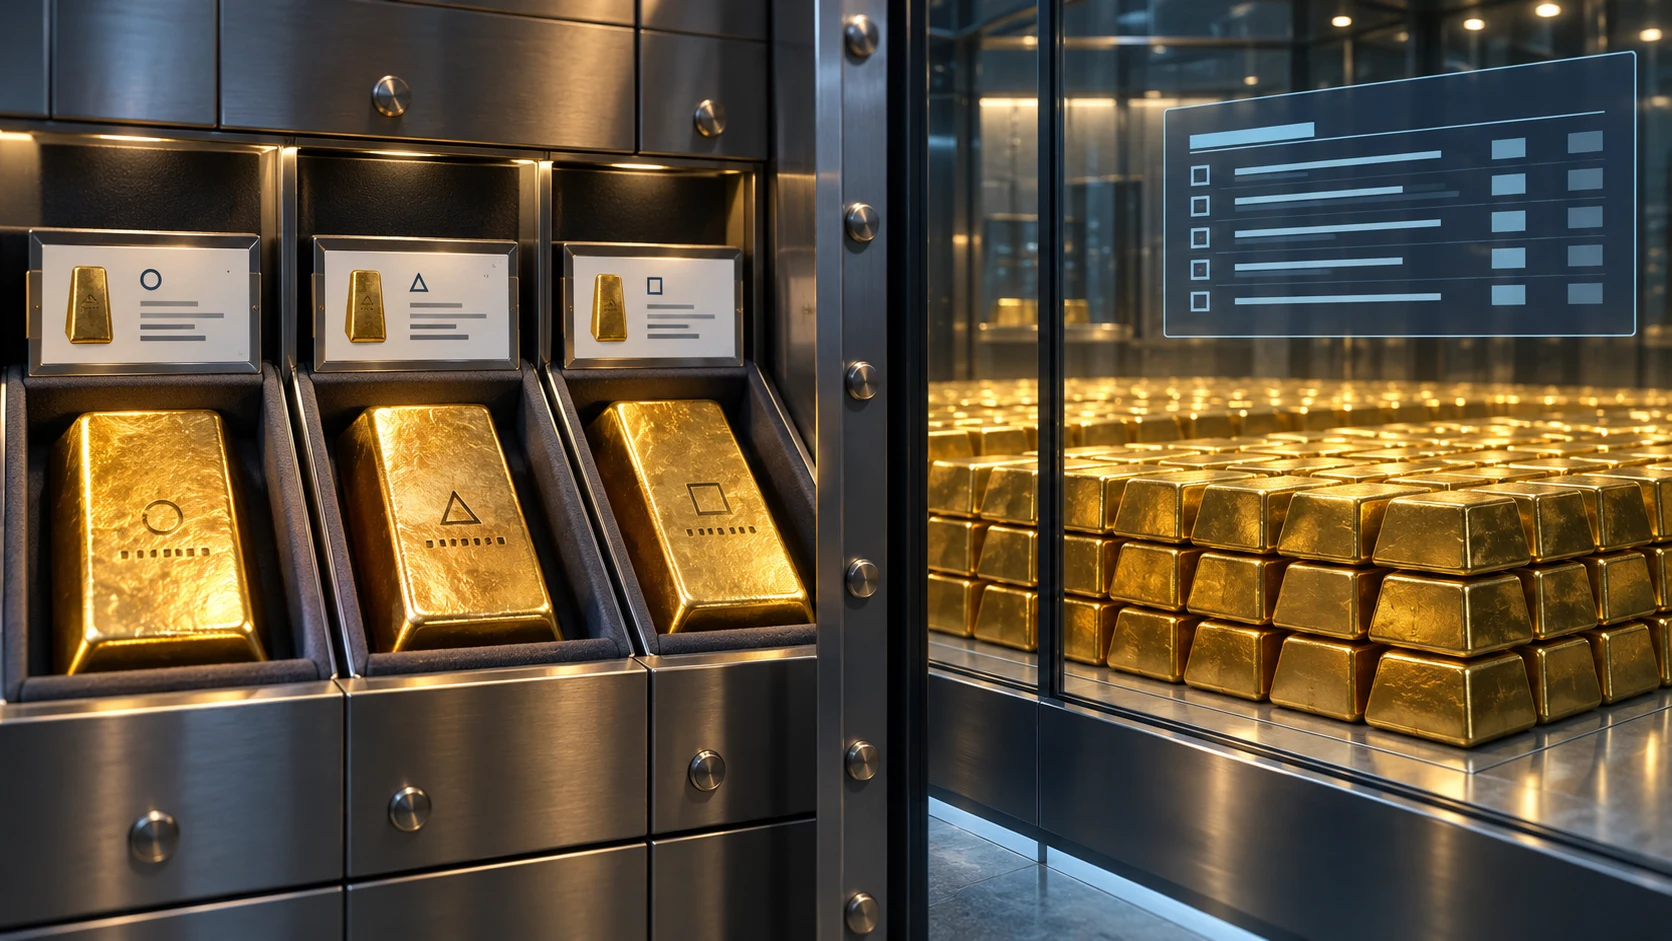
The most important difference between allocated and unallocated gold is not where the metal sits. It is the legal and accounting relationship between you, the provider, and the bullion.
With an allocated account, specific bars are identified for the customer, and the customer generally holds title to that metal while the dealer or vault acts as custodian. With an unallocated account, no particular bars are assigned. The customer normally has a contractual claim against the account provider for a quantity of gold.
That distinction affects counterparty risk, recordkeeping, costs, transfers, and what may happen if the provider becomes insolvent. The exact outcome always depends on the contract and governing law, so the account label alone is not enough.
What is allocated gold?
The London Bullion Market Association defines an allocated account as one used when a customer requires physically segregated metal and a detailed list of bar weights and other identifying information. The client has full title to the metal, and the dealer holds it as custodian.
For large wholesale bars, an allocation record may include the refiner, serial number, assay or fineness, gross weight, and fine-gold weight. The point is that the account can identify which bars belong to its owner rather than merely recording an ounce balance.
An allocated arrangement does not necessarily mean the customer can walk into a vault without notice. Access, withdrawal, inspection, delivery, and sale still follow the custody contract. Large bars may also be impractical for a retail customer to withdraw or divide.
What is unallocated gold?
An unallocated account records a general entitlement to a quantity of metal without assigning specific bars. The LBMA compares it with a bank currency account: the balance shows what the institution owes the account holder, not a list of particular objects held in the customer’s name.
The LBMA says most wholesale over-the-counter bullion trading in London clears through unallocated accounts. They are efficient because dealers can settle trades by crediting and debiting accounts instead of moving heavy bars for every transaction.
Efficiency changes the risk structure. The LBMA’s market guide says an unallocated account holder has a contractual claim against the clearer and therefore has credit exposure to the institution where the account is held.
Put simply:
- Allocated: “These identified bars are held for this owner.”
- Unallocated: “This provider owes this account an amount of gold.”
Why does insolvency treatment matter?
If a custodian fails, the legal question is whether the customer owns identified property or is a creditor with a claim against the failed institution.
An SEC-filed gold-trust prospectus provides a useful real-world explanation. It states that gold in an unallocated account is not segregated from the custodian’s assets. During the periods in which the trust or an authorized participant uses that unallocated account, it has no proprietary right to specific bars and is an unsecured creditor for that balance.
The same filing says the trust retains legal title to its allocated bars. Even then, insolvency could create delays and costs while a liquidator, trustee, or court identifies and releases the metal. Allocation can reduce direct credit exposure to the custodian, but it does not eliminate legal, operational, fraud, access, or recovery risk.
U.S. buyers should not assume every provider uses LBMA wording or English-law treatment. Read the actual customer agreement and determine which jurisdiction governs it.
Does “physically backed” mean the same as “allocated to me”?
No. A product may be physically backed while the investor owns a security or contractual interest rather than specific bars.
For example, a gold trust can hold identified, allocated bars as trust property. A retail shareholder typically owns shares in the trust, not direct title to a chosen bar on the vault list. Creation and redemption mechanics may also use temporary unallocated accounts, even when the trust aims to finish each business day with its gold allocated.
That is why these statements can all be true at the same time:
- The trust owns allocated physical gold.
- The custodian holds identified bars for the trust.
- A retail investor owns shares, not those individual bars.
- Unallocated accounts may be used briefly for settlement.
Our guide [Can You Redeem a Gold ETF for Physical Gold?](/blog/can-you-redeem-gold-etf-for-physical-gold) explains the difference between trust-level bullion and a shareholder’s rights.
Why might someone choose allocated gold?
Allocated custody may appeal to a buyer whose priority is clear title to identified metal and reduced balance-sheet exposure to the dealer or custodian.
Potential advantages include:
- Specific bars or units are identified in account records.
- The customer generally retains title rather than holding only a general metal claim.
- Regular bar lists and reconciliation can improve transparency.
- Properly structured custody may keep the metal separate from the custodian’s own inventory.
Potential disadvantages include:
- Storage, insurance, audit, and handling fees may be higher.
- Delivery can involve notice periods, fabrication, shipping, and minimum sizes.
- Selling or transferring specific bars may be less frictionless than moving an account balance.
- Custodian, subcustodian, documentation, jurisdiction, and access risks remain.
Why might someone choose unallocated gold?
Unallocated accounts can make wholesale trading and settlement faster and less expensive. They may permit small or fractional ounce balances without assigning an entire bar.
Potential advantages include:
- Lower custody and transaction costs in some arrangements.
- Efficient trading, settlement, and transfers.
- Easier handling of fractional balances.
- No need to move or reassign physical bars for every transaction.
Potential disadvantages include:
- The holder usually has a general claim, not title to specific bars.
- The account creates credit exposure to the provider.
- Insolvency may leave the customer as an unsecured creditor.
- Withdrawal may depend on minimums, availability, conversion fees, and contract terms.
Lower cost is not automatically better if the account structure does not match the buyer’s reason for owning gold.
A practical example
Suppose Alex pays for 10 ounces of gold held in an allocated account. The statement identifies the bars or units, the custody agreement says Alex retains title, and the provider acts only as custodian.
Jordan instead has a 10-ounce credit in an unallocated account. No bars are listed. The provider owes Jordan the equivalent of 10 ounces under the account contract and may settle a sale or withdrawal through its general pool.
If gold rises 5%, both balances might show a similar price gain before costs. But their legal positions are different. Alex’s principal concern is recovering identified property from custody. Jordan also depends on the provider’s ability to satisfy its contractual metal obligation.
The example does not prove that every allocated service is safe or every unallocated service is unsuitable. Provider quality, contract language, fees, insurance, audits, jurisdiction, and intended holding period all matter.
Questions to ask a gold-storage provider
Before sending money, ask for written answers:
1. Is my gold allocated or unallocated under the contract? 2. Do I receive legal title to specific bars or only a contractual metal balance? 3. Will I receive a bar list with serial number, refiner, fineness, and weight? 4. Is customer metal separated from the provider’s assets and trading inventory? 5. Who is the vault operator, custodian, and any subcustodian? 6. Which country’s law governs the custody agreement? 7. What happens to my claim if the dealer, custodian, or vault operator becomes insolvent? 8. Are holdings independently audited or reconciled, and are reports available? 9. What insurance exists, what events are excluded, and who is the beneficiary? 10. What are the storage, transaction, fabrication, delivery, assay, and withdrawal fees? 11. Is there a minimum quantity for physical withdrawal? 12. Can the provider lease, pledge, lend, or otherwise encumber customer metal?
The CFTC and FINRA also advise physical-metals buyers to verify dealers, compare total costs, avoid high-pressure sales tactics, and be skeptical of promises that precious metals are low-risk or guaranteed to profit.
Costs can change the choice
Allocated custody often charges explicit storage and insurance fees. Unallocated services may advertise lower storage costs, but their economics can include spreads, account charges, withdrawal fees, or compensation for taking provider credit risk.
Compare the full round trip:
- purchase premium or dealing spread;
- annual custody or account fee;
- minimum charge;
- sale spread;
- fabrication or conversion cost;
- delivery and insurance;
- assay fees; and
- applicable taxes.
For a worked break-even framework, see [How Gold Bullion Premiums Affect Returns](/blog/gold-bullion-premiums-break-even-calculation).
Frequently asked questions
Is allocated gold safer than unallocated gold?
Allocated gold generally reduces direct credit exposure to the account provider because specific metal is held for the owner. It still carries custody, fraud, documentation, access, insurance, and legal-enforcement risks. “Safer” depends on the provider and contract, not just the label.
Can I take delivery from an unallocated account?
Possibly, but only under the provider’s terms. The account may need to be converted into allocated bars or retail products, with minimum quantities, fabrication charges, shipping, and delays.
Does a bar list prove ownership?
It is important evidence, but it should agree with the custody agreement, invoices, account statements, and independent reconciliation. A fabricated list does not create legal title.
Is gold in my home automatically allocated?
If you bought and possess identifiable bullion outright, it is your property rather than an account balance. Home possession introduces different risks, including theft, damage, insurance limits, authentication, and resale logistics.
Does buying a gold ETF give me allocated gold?
Usually, a retail investor owns fund or trust shares. The vehicle may hold allocated bullion, but shareholders generally do not own specific bars and may not have retail redemption rights. Check the prospectus.
Sources and methodology
This evergreen article was reviewed on October 22, 2026. It uses market-structure definitions from the LBMA, risk language from SEC-filed gold-trust disclosures, and consumer guidance from U.S. regulators. Account rights vary by provider, contract, and jurisdiction.
- [LBMA: Precious Metal Accounts](https://www.lbma.org.uk/publications/the-otc-guide/precious-metal-accounts)
- [LBMA: About Loco London—Allocated and Unallocated Accounts](https://www.lbma.org.uk/market-standards/about-loco-london)
- [LBMA Glossary: Unallocated and Allocated Accounts](https://www.lbma.org.uk/resources/glossary)
- [SEC filing: Gold trust custody and allocation risks](https://www.sec.gov/Archives/edgar/data/1222333/000119312522257655/d236982d424b3.htm)
- [CFTC and FINRA: 10 Things to Ask Before Buying Physical Precious Metals](https://www.cftc.gov/LearnAndProtect/AdvisoriesAndArticles/Metals10Things.html)
- [CFTC: Gold Is Not Always a Safe Investment](https://www.cftc.gov/LearnAndProtect/AdvisoriesAndArticles/gold_is_no_safe_investment.htm)
This material is educational and does not provide personalized investment, legal, or tax advice.